
(Originally reported by Modern Retail)
Executive Overview
For decades, multinational conglomerates operating within the Fast-Moving Consumer Goods (FMCG) sector maintained a rigid separation between divisions. Food, personal care, and wellness existed in distinct corporate silos, governed by predictable consumer habits and linear marketing strategies. However, the modern consumer has fundamentally dismantled these boundaries. Today, the line separating looking good from feeling good has evaporated, replaced by an integrated, holistic philosophy where appearance is inextricably tied to internal vitality.
At the epicenter of this transformation is Unilever. Speaking at the flagship Groceryshop conference in Las Vegas, Jostein Solheim, CEO of Unilever Wellbeing, outlined a paradigm shift that is reshaping how one of the world’s largest consumer goods companies approaches product development, brand acquisition, and consumer engagement. According to Solheim, modern consumers—particularly younger demographics such as Millennials and Generation Z—are no longer content with superficial beauty routines or reactive healthcare. Instead, they are demanding a science-backed, personalized convergence of beauty, health, and daily wellness.
This profound cultural shift has forced legacy giants to pivot aggressively. Once historically recognized as a titan of packaged foods, Unilever has steadily rearchitected its product portfolio. Through a series of calculated, high-stakes acquisitions—starting with Olly in 2019 and culminating in the recent purchase of Grüns—Unilever Wellbeing has quietly assembled a powerhouse stable of preventative health and nutrition brands. Driven by the digitalization of health data, the mainstreaming of GLP-1 weight-loss medications, and a cultural fixation on longevity, this strategic pivot illustrates how legacy CPGs must evolve or risk obsolescence in an era where wellness is the ultimate currency.
Detailed Chronology: The Evolution of Consumer Health and Beauty
To understand Unilever’s aggressive positioning in the wellness sector, one must examine the historical trajectory of how consumers perceive health, diet, and beauty. Solheim outlined a fascinating, three-phase evolution that has taken place over the last half-century, completely rewriting the playbook for consumer packaged goods.
Phase 1: The Era of Superficial Appearance
Looking back ten years, the definition of "beauty" was remarkably narrow. It was almost exclusively defined by external appearance. Marketing departments across the globe pedaled topical solutions—creams, lotions, and cosmetics—designed to mask flaws or enhance features without addressing physiological health. Simultaneously, dieting was viewed through the same superficial lens. Individuals altered their caloric intake or food consumption primarily for aesthetic outcomes: fitting into a specific clothing size or altering body shape for an upcoming social event. Health was a byproduct, not the primary objective.
Phase 2: The Disease Prevention and Internal Wellness Pivot
The first major structural shift occurred as public consciousness around chronic illness, weight management, and nutrition evolved. Diets shifted from being strictly appearance-driven to being motivated by health reasons. Consumers began setting health goals focused on weight management and physiological optimization as a direct means to prevent future diseases and medical ailments.
This laid the groundwork for the second major shift: the undeniable convergence of beauty and well-being. Consumers rapidly adopted a holistic mindset, realizing a foundational truth: you cannot feel truly beautiful if you do not feel good on the inside. This realization sparked a democratization of health, where individuals began taking proactive agency over their daily well-being. Wellness was no longer reserved for annual physicals or clinical environments; it was integrated into everyday life, offering brands an unprecedented opportunity to forge deeper, more meaningful emotional connections with their customer base.
Phase 3: The Digitalization of Wellness and Scientific Access
The most recent evolutionary leap has been supercharged by technology. The digitalization of health data, the proliferation of wearable tech, and the democratization of scientific research have put unprecedented power into the hands of the everyday consumer.
"When consumers have all this information and data in their hands, they can access science at a whole new level," Solheim noted during his Groceryshop keynote.
This technological democratization means consumers are no longer passive recipients of marketing claims. They cross-reference ingredient lists, analyze clinical trials, and demand absolute transparency. Combined with the massive cultural accelerators of AI-assisted health monitoring and the meteoric rise of GLP-1 weight-loss drugs, today’s consumer is hyper-informed, highly proactive, and relentlessly demanding when it comes to personal health outcomes.
Supporting Context & Metrics: Portfolio Transformation at Unilever
Unilever’s corporate evolution serves as a masterclass in adapting to structural market shifts. Historically pigeonholed as a traditional food and household goods behemoth, the company recognized that future growth required a deliberate diversification into "better-for-you" categories.
The M&A Playbook: Building a Wellbeing Empire
Unilever’s aggressive entry into the modern wellness space began in earnest in 2019 with its acquisition of Olly, a brand Solheim describes as "the original disruptor of the vitamin shelf." Olly successfully transformed mundane, clinical-looking vitamin supplements into vibrant, lifestyle-oriented wellness products that consumers actually wanted to display on their countertops.
Fast forward to the present day, and Unilever Wellbeing boasts a formidable portfolio comprising seven distinct wellness-oriented brands. Within this ecosystem, four have been designated by Unilever executives as "power brands":
- Olly: The pioneer of lifestyle-centric vitamins and mood-support supplements.
- Liquid I.V.: The dominant force in advanced hydration and science-backed electrolyte delivery systems.
- Nutrafol: A clinically tested, physician-formulated brand targeting the root causes of hair thinning and loss—a prime example of beauty meeting internal health.
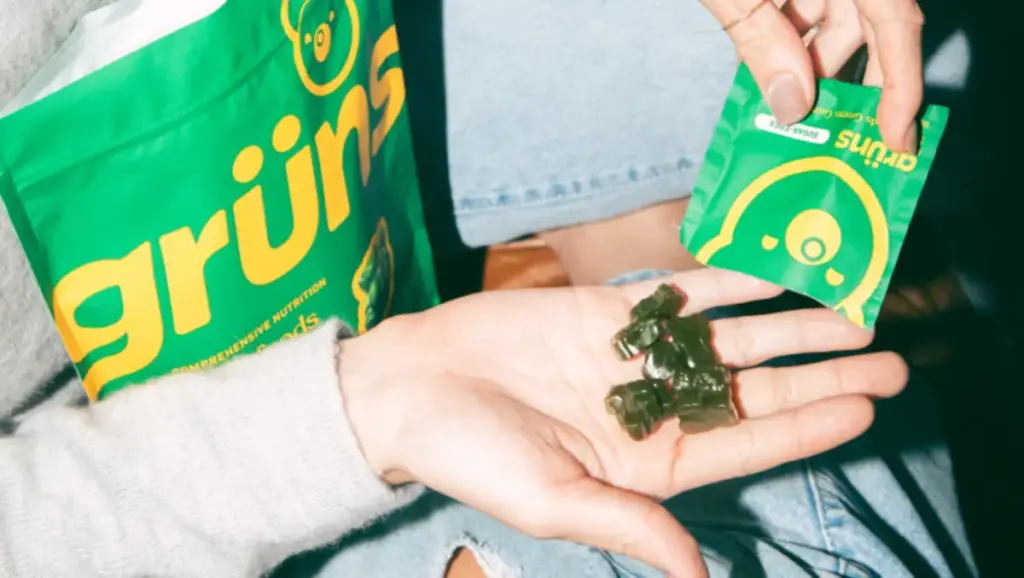
- Grüns: The latest addition to the portfolio, acquired earlier this year, specializing in nutrient-dense daily nutritional gummies.
Navigating the GLP-1 Era and Nutritional Gaps
The modern supplement landscape is increasingly shaped by macro-trends in weight management, most notably the widespread adoption of GLP-1 receptor agonists (such as Ozempic and Wegovy). While these pharmaceuticals have revolutionized weight loss, they often introduce unintended nutritional side effects, such as dramatic reductions in caloric intake, muscle mass loss, and severe fiber or micronutrient deficiencies.
This is precisely where Unilever’s recent portfolio additions find strategic alignment. Highlighting the newly acquired Grüns brand, Solheim offered a sharp industry insight:
"A product like Grüns is probably your GLP’s best friend."
With a single serving providing six grams of dietary fiber alongside 21 essential vitamins and minerals, products like Grüns bridge the nutritional deficits created by modern weight-loss regimens. These targeted formulations directly address contemporary consumer needs for comprehensive health, sustained nutrition, and metabolic support in an era dominated by longevity goals.
Furthermore, Solheim addressed the historical elephant in the room: the supplements category has long suffered from "overclaims" and a lack of clinical rigor. Because the human physiological system is exceptionally complex—meaning what works wonders for one individual may have zero impact on another—consumers are increasingly rejecting one-size-fits-all solutions. They are actively seeking hyper-personalized, science-backed regimens that cater to their unique biological makeup.
Official Statements and Industry Insights
The insights shared by Jostein Solheim at Groceryshop illuminate not just Unilever’s internal strategy, but the broader psychological currents moving modern global commerce. By listening closely to the shifts in consumer behavior, Unilever has positioned itself at the vanguard of preventative healthcare and lifestyle CPG.
On the shifting definitions of beauty and health, Solheim emphasized:
"When you go back 10 years, beauty was very much defined as appearance… Now we’re on a diet for wellness and beauty."
He further underscored the psychological integration of internal health and external aesthetics:
"You can’t feel beautiful if you’re not feeling good inside."
Detailing the modern consumer’s psychological shift toward taking control of their destiny, Solheim noted:
"That gave an opportunity for branding and building deeper relationships. When consumers have all this information and data in their hands, they can access science at a whole new level."
Addressing the historical credibility challenges of the supplement industry, Solheim pointed out the critical need for authenticity:
"The human body is complicated, so what works for somebody might not work for somebody else."
Finally, emphasizing the commercial imperative of capturing younger demographics early in their lifecycle, Solheim explained:
"The whole well-being industry is [now] being driven by Gen Zs, with the trend having first started with Millennials. You will see people in their 30s and their 40s talking about longevity, talking about healthy aging and setting the groundwork for healthy aging. Whereas if somebody comes to the brand at age 65 to start that journey, that’s a tough business opportunity."
Future Outlook: The Longevity Economy and CPG Strategy
As we look toward the future of the consumer packaged goods industry, the implications of Unilever Wellbeing’s strategic thesis are profound. The traditional marketing funnels of the 20th century—built around demographic generalizations and superficial aspirations—are being entirely replaced by data-driven, wellness-first ecosystems.
Engaging the Longevity-Obsessed Consumer
The most significant takeaway from Solheim’s keynote is the radical shift in when consumers begin thinking about aging and health. Historically, anti-aging and longevity products were marketed reactively to older demographics navigating age-related decline. Today, that timeline has been dramatically compressed.
Driven by digital native generations—Millennials and Gen Z—longevity has become a lifelong proactive pursuit. Consumers in their twenties and thirties are actively investing in preventative care, sleep optimization, metabolic health, and nutritional supplementation to protect their biological future decades down the line. For CPG giants, this represents an extraordinary commercial runway. By establishing brand loyalty during these formative early stages, companies can secure multi-decade consumer relationships. As Solheim bluntly noted, waiting until a consumer reaches retirement age to introduce them to a health and wellness journey represents an uphill battle.
The Road Ahead for Unilever and the CPG Landscape
Moving forward, the successful consumer brands will not be those that merely sell products, but those that serve as trusted partners in holistic life optimization. The boundaries between food, pharmaceuticals, cosmetics, and wellness will continue to dissolve completely.
For Unilever, the aggressive integration of power brands like Olly, Liquid I.V., Nutrafol, and Grüns proves that legacy conglomerates can successfully pivot away from rigid legacy models. By embracing science, personalization, and the unyielding cultural demand for internal well-being, Unilever is not merely reacting to the future of consumer health—it is actively engineering it. As wellness transitions from an emergent trend to the core foundational pillar of beauty and personal care, the lessons learned in Las Vegas this week will reverberate across the global CPG landscape for years to come.